

Valuable Items Insurance
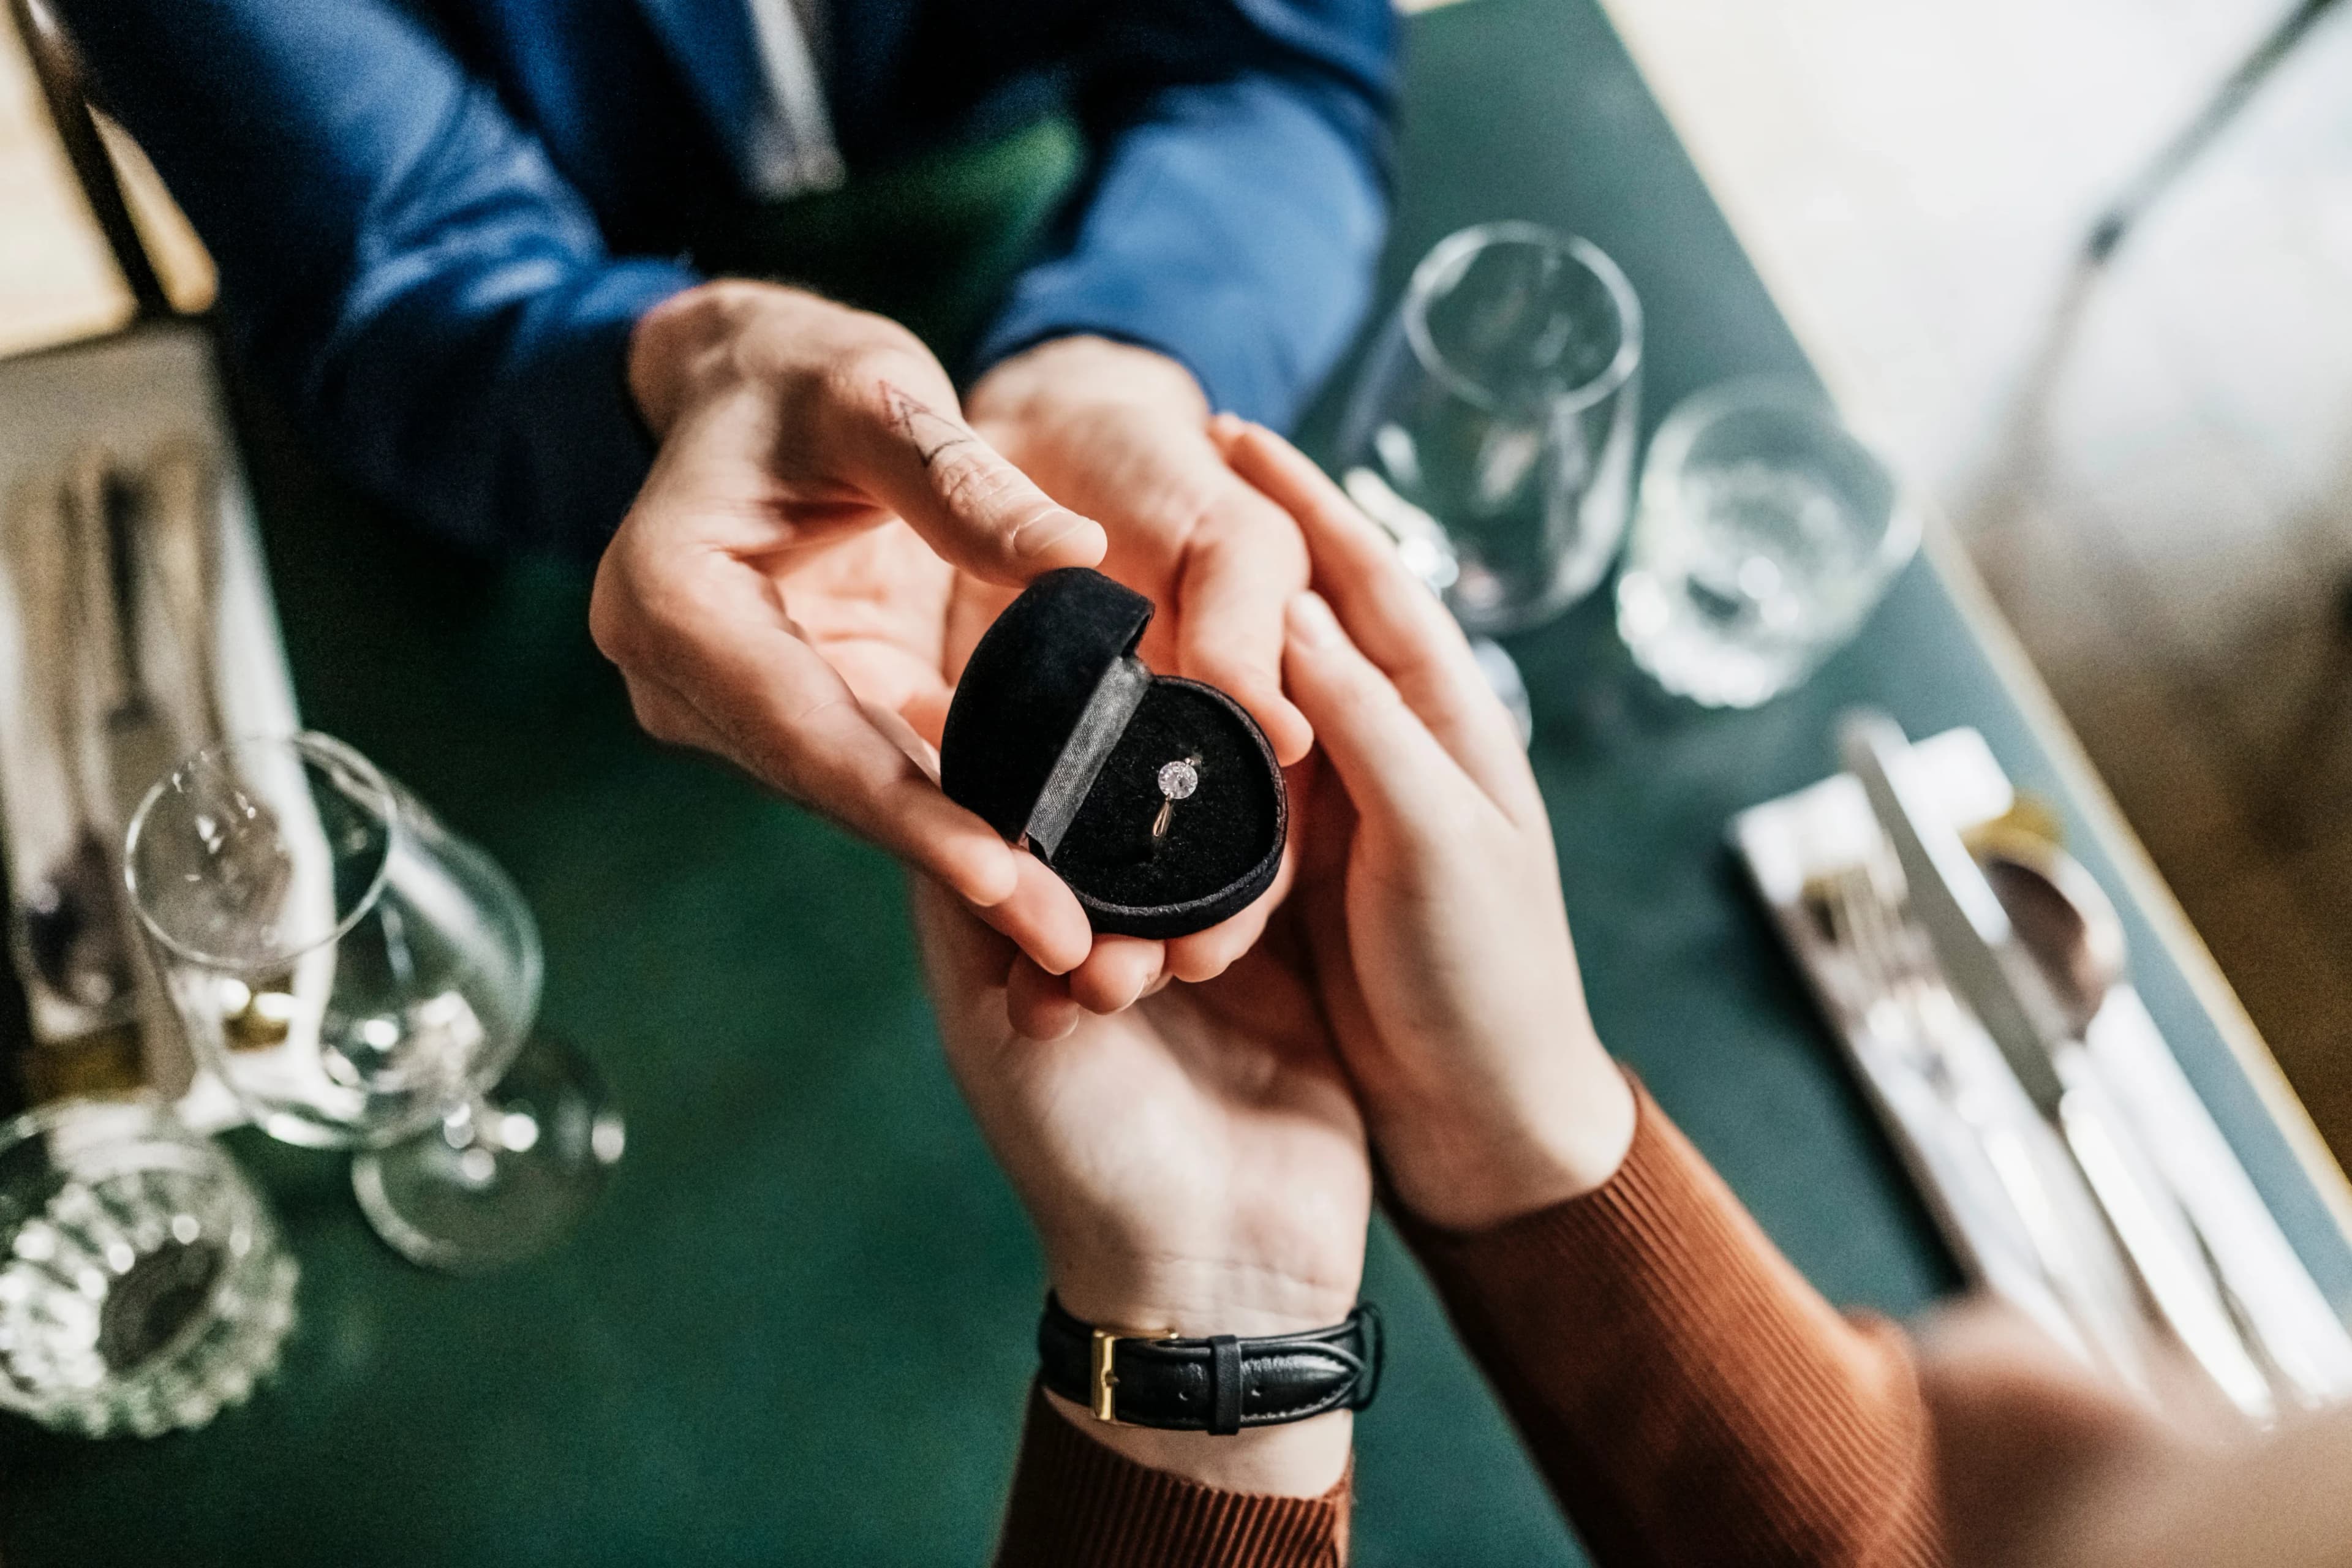
Your homeowners policy typically caps jewellery and fine art coverage at a few thousand dollars, no matter what your collection is worth. HUB schedules each item at its real, appraised value, with an advocate on your side if you ever need to file a claim.
Important Considerations
Where valuable items need specialized protection
Insuring valuable items raises questions your other coverage doesn't. From finding a carrier willing to write this coverage to keeping your schedule current as your collection grows, an advisor makes the difference.
Homeowners policies cap jewellery, fine art, and collectibles well below typical appraised value, often under one shared sub-limit. Comparing that limit to current value — before a loss, not after — keeps coverage accurate as a collection grows.
Jewellery is typically capped on a per-item basis, while fine art and collectibles are often bundled under a single shared limit that doesn't distinguish between pieces. As a collection grows or gains value, these fixed caps stay the same, so the distance between what's covered and what's owned widens over time. Reviewing coverage as a collection changes keeps it in step with current value.
Scheduling individual pieces — or adding a valued-items rider — sets coverage to each item's appraised value instead of the homeowners policy's blanket sub-limit, and an annual review keeps that value current as collections grow or market prices shift.
Most people have a good idea of what their jewellery is worth. But many don’t know which insurance companies will cover it or what paperwork is needed. That’s often where gaps in coverage happen without the right guidance.
Each item is insured based on its current value, so if it’s lost, the payout reflects what it’s worth, rather than a standard limit that may not fully cover it.
Homeowners policies bundle jewellery, art and collectibles into one personal-property limit that most households assume covers their most valuable pieces individually. It doesn't. A scheduled rider has to be placed alongside the homeowners policy, and the two are easy to lose track of as a collection grows.
When a household files a claim on a treasured watch, a painting or an heirloom ring, many discover the hard truth too late: their homeowners policy caps all personal property under a single dollar limit, and that ceiling rarely reflects what any one item is truly worth. Full protection for those standout pieces lives in a separate scheduled rider that runs parallel to the main policy. As a collection keeps growing, keeping both aligned turns into a quiet, ongoing challenge that's easy to overlook until coverage falls short.
Placing the scheduled rider through the same broker who manages the homeowners policy keeps the two coordinated — new pieces get added to the schedule as they're acquired, rather than sitting unprotected under the personal-property limit until the next renewal surfaces the shortfall.
Collectors add pieces faster than they update policies — the schedule is only as good as the last time someone checked it against the homeowners renewal.
The scheduled rider and the homeowners policy move together, so a newly acquired piece is protected from the day it enters the collection rather than left exposed under the personal-property limit.
The market for fine art, jewellery, and collectibles coverage is more limited than standard homeowners insurance, with fewer insurers offering these specialized policies.
Independent access to the smaller set of carriers that specialize in fine art, jewellery and collectibles — rather than relying on whichever insurer already writes the household's homeowners policy — lets an advisor place coverage a single carrier relationship might not offer at all.
Independent access to the smaller set of carriers that specialize in fine art, jewellery and collectibles — rather than relying on whichever insurer already writes the household's homeowners policy — lets an advisor place coverage a single carrier relationship might not offer at all.
A household's home and auto carrier isn't necessarily the right carrier for a valuable collection — knowing which insurers specialize in scheduling fine art or jewellery matters more here than almost anywhere else in personal lines.
The household's collection is placed with a carrier that genuinely specializes in valuable items, rather than bundled by default with whichever insurer already holds the home and auto business.
A jewelry or fine art claim depends on proving what the item was worth — through an appraisal, receipt or certificate of authenticity — at the time of loss. Without current documentation, a household can find itself negotiating actual cash value instead of collecting the replacement cost it expected.
When a valuable item is lost or damaged, the payout hinges on the records kept before the loss. Up-to-date proof of value — an appraisal, receipt, or certificate of authenticity — is what secures a full replacement-cost settlement. Fall short on documentation, and the claim can quietly default to actual cash value, leaving the policyholder with far less than expected.
Keeping appraisals, receipts and photographs current — and confirming the policy pays replacement cost rather than actual cash value — turns a claim into a documented transaction instead of a negotiation, with a broker who can bring in specialist adjusters when a piece's value is in question.
The claim rarely turns on whether the loss happened — it turns on whether anyone can prove, on the day of the loss, what the piece was worth.
The household collects the item's full appraised replacement value without a dispute, because the documentation was already in place well before the loss ever occurred.
Other Coverage Considerations
Helping you build a more complete protection strategy
Insights for You
Valuable items insurance insights and resources
